

One of the questions we hear most often is simple: What do paid subscribers actually receive?
Rather than describe it, we thought it would be better to show you.
So we are making our latest Opportunity Report available so you can see for yourself.
At Boyar Research, our mission is to produce thoughtful, in-depth research focused on businesses we believe are misunderstood, underfollowed, or trading at a meaningful discount to intrinsic value.
If you find this report valuable and would like access to all of our premium research, we are offering 25% off an annual subscription for the next seven days using the link below.
Sincerely,
Jonathan Boyar
Key Highlights
Cooper operates two segments: CooperVision (CVI, ~67% of revenue), the world’s #2 or #3 soft contact lens manufacturer with an estimated ~25% share of a four-company global oligopoly, and CooperSurgical (CSI, ~33%), a diversified fertility and women’s health business spanning more than 600 products.
The global contact lens market is projected to grow at a 6.5% CAGR between 2024 and 2032 (from ~$11 billion to ~$18.3 billion), an acceleration from the 4%-6% range in recent years driven by an aging population, expanding access to underpenetrated regions, and a rising incidence of myopia tied to increased digital device usage.
Myopia is a large and growing ailment, affecting approximately one-third of the population currently and an estimated half by the year 2050. Cooper’s MiSight lens is the only FDA-approved contact lens proven to slow myopia progression in children, and has generated impressive growth rates, with revenue increasing 30% in fiscal 2025 and guidance of at least 20%-25% growth in fiscal 2026. Cooper also has a JV with EssilorLuxottica for the SightGlass Vision eyeglass lens, which holds FDA Breakthrough Device designation and remains in the U.S. approval process.
Two activist investors—JANA Partners (~1.2% stake) and Browning West (~3.5%)—have been pushing Cooper for change, publicly scrutinizing the Company’s performance. This has led to corporate governance changes, a formal strategic review, and an increase in share repurchases.
After a hiatus from share repurchases in fiscal years 2023 and 2024, Cooper resumed buybacks in fiscal 2025 and increased its buyback authorization to $2 billion. This is supported by an acceleration in free cash flow over the coming years, as the MyDay contacts production facilities expansion has completed. CEO Albert White also personally purchased 10,000 shares in September 2025 at approximately $68.
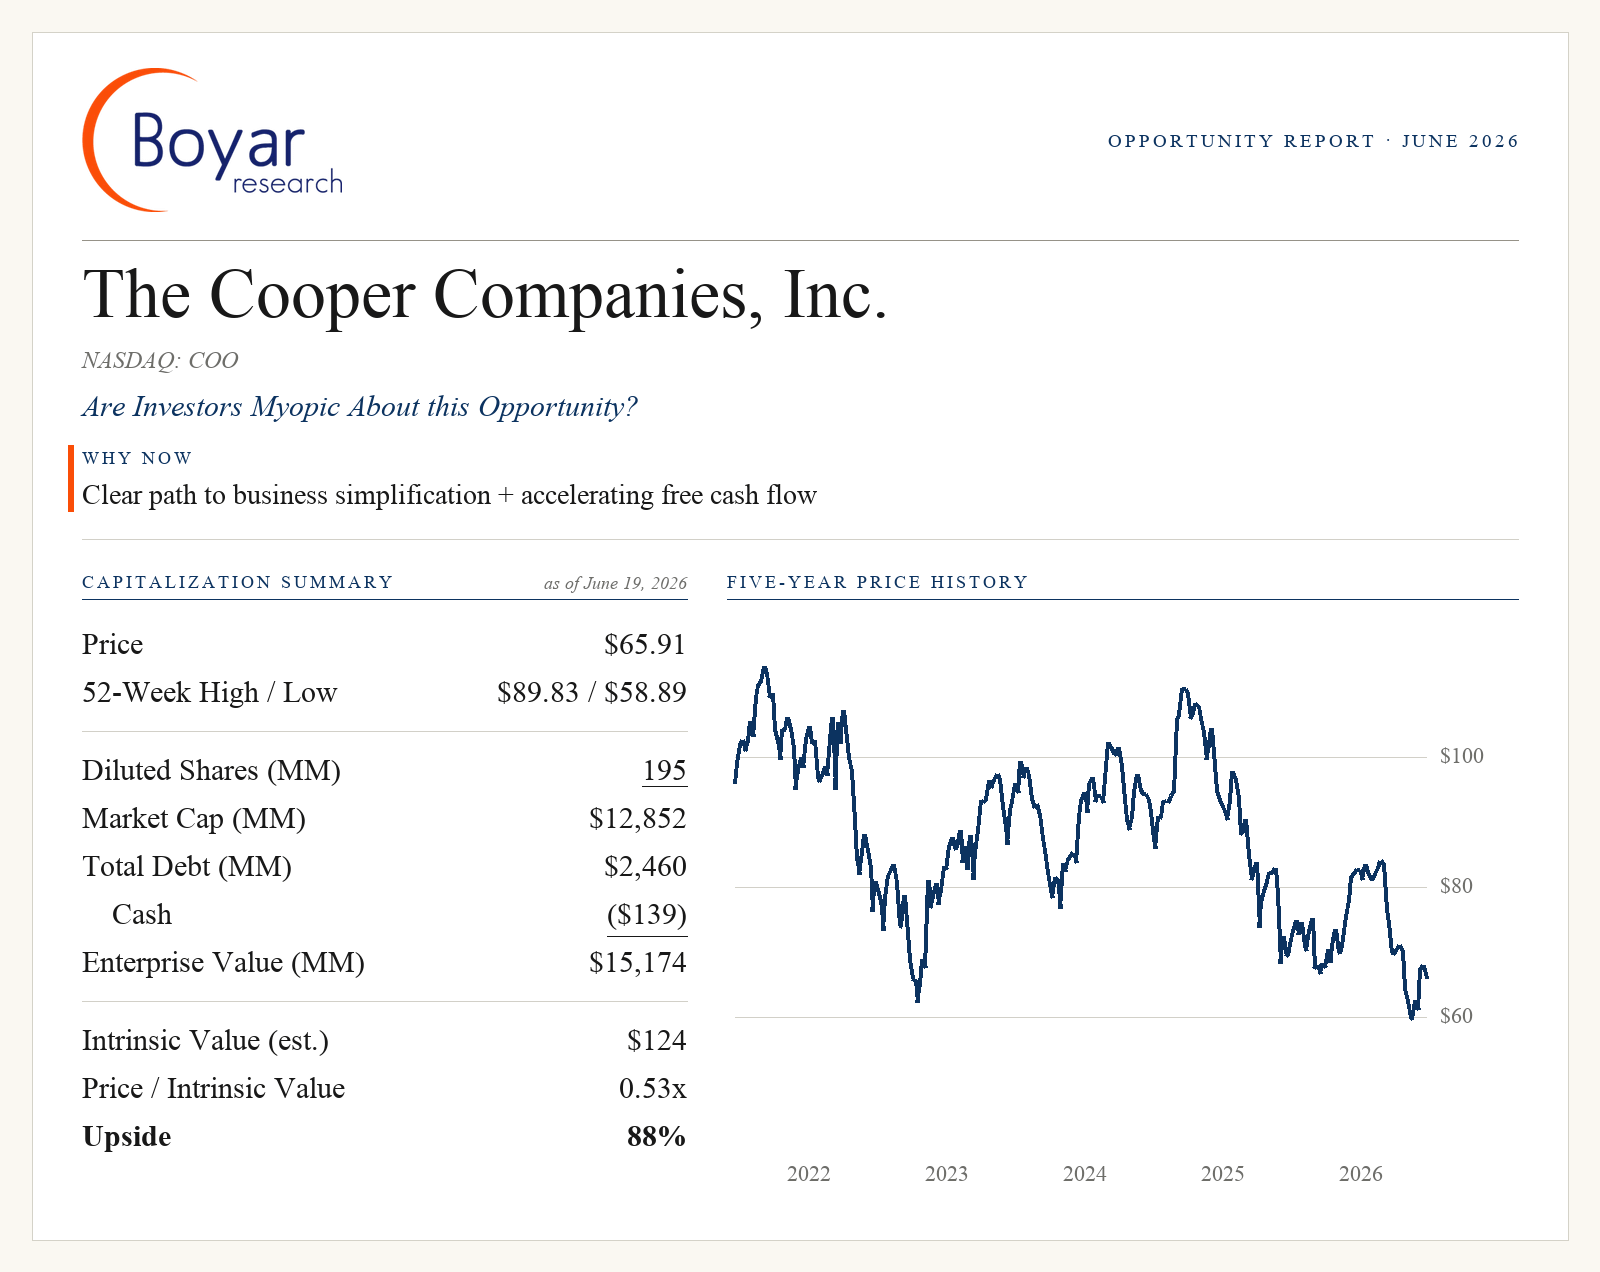
Valuation: Applying an 18x multiple to our FY 2027E EBITDA, we derive an intrinsic value of $124 per share, representing 88% upside.
Company History
Cooper’s roots trace back to 1958, when its predecessor, Martin H. Smith Co., focused on oral and skin care products. The Company was incorporated as Cooper Tinsley Laboratories in 1961, renamed Cooper Laboratories in 1967, and entered the contact lens business in 1972 through the acquisition of GlobalVision. In 1979, its Permalens lens became the first contact lens approved by the FDA for up to 30 days of continuous wear, and by 1980 the Company had organized into three divisions, including the original CooperVision unit. Cooper went public in January 1983 and, later that year, acquired UCO Optics and its Aquaflex brand—only the third soft contact lens ever approved by the FDA—cementing an early foothold in the category. The Company adopted its present name, The Cooper Companies, Inc., in 1987, and formed its second segment, CooperSurgical, in 1990 through the acquisition of cryosurgery products maker Frigitronics.
Since 2000, Cooper has completed roughly 50 acquisitions, four of which exceeded $1 billion in value: Ocular Sciences (2005, ~$1.1 billion), which nearly doubled CooperVision’s revenue base and made it the world’s third-largest contact lens company at the time; Sauflon Pharmaceuticals (2014, ~$1.2 billion), a European daily-lens manufacturer; Teva’s PARAGARD IUD business (2017, ~$1.1 billion), which added the only long-lasting, hormone-free IUD then approved in the U.S.; and Generate Life Sciences (2021, ~$1.6 billion), a donor egg/sperm and cryopreservation business that materially expanded CooperSurgical’s fertility platform.
Business Overview
The Company operates in two business segments:
CooperVision (CVI; 67% of FY 2025 sales) manufactures soft contact lenses sold across three regions—Americas (the largest), EMEA, and Asia Pacific—under brands including Biofinity (its top-selling monthly silicone hydrogel lens), MyDay (its premium single-use line, recently expanded into multifocal and toric variants), Avaira Vitality, and clariti (its value-priced daily offering). Toric and multifocal lenses, which correct more complex visual defects such as astigmatism and presbyopia in addition to standard near- and far-sightedness, made up roughly 49% of segment revenue in fiscal 2025 and have been growing faster than the spherical category. CVI also produces private-label lenses for retailers such as LensCrafters and Pearle Vision.
CooperSurgical (CSI; 33%) addresses fertility and women’s health through two reporting categories: Office/Surgical (~61% of segment revenue), which includes gynecological devices, the PARAGARD IUD, and labor-and-delivery and cord-tissue storage products sold mainly through OB/GYN providers; and Fertility (~39%), which includes IVF-related devices, donor egg and sperm services, cryopreservation, and genetic testing sold primarily to fertility clinics. The segment’s growth has benefited from rising use of assisted reproductive technology, as patients increasingly delay childbearing, alongside expanding fertility benefits coverage.
Profitable Oligopoly with Durable Tailwinds
CooperVision competes in a global contact lens market with just four meaningful players—Johnson & Johnson (~35% share); Alcon and CooperVision (~25% each); and Bausch Health (~10%)—a structure that confers high barriers to entry, sticky brand loyalty, and long product life cycles.
It is also a structural growth market: a recent industry report from Fortune Business Insights projects the global contact lenses market to grow from ~$11 billion in 2024 to $18.3 billion in 2032, representing an attractive 6.5% CAGR. This is an acceleration from the historical market growth of 4% to 6% due to an aging population, growing access to contacts in many regions of the world and a continued rise in myopia (especially in younger children) due to increased digital usage. As CEO White noted, “a little over a third of people are myopic and half of people are going to be myopic by the year 2050.”
Cooper is arguably the best-positioned company to address this trend. MiSight, its one-day lens, remains the only FDA-approved product that slows myopia progression in children, and its growth has accelerated meaningfully (guidance of 20%-25% in fiscal 2026, following 30% growth in fiscal 2025). The Company’s joint venture with EssilorLuxottica, SightGlass Vision, complements MiSight with an eyeglass lens that has been designated as an FDA Breakthrough Device for reducing myopia progression in children—giving Cooper a presence across both major treatment modalities for pediatric myopia, a market still in its early stages of treatment in the U.S.
CooperSurgical’s fertility business benefits from a separate but equally durable tailwind: rising use of assisted reproductive technology, which grew at an ~10% CAGR (measured in treatment cycles) in the U.S. from 2013 to 2022, alongside increased fertility-benefits coverage and later average childbearing age.
An Activist Shake-up and Strategic Review
Beyond corporate overhead, Cooper’s two business segments share very little synergy (such as manufacturing, sales, or distribution). The combination of these siloed businesses and an underperforming stock price has attracted the attention of two activist investors. In 2025, JANA Partners built a stake of just over 1% in the Company and floated combining CooperVision with Bausch + Lomb, the fourth-largest player in the contact lens oligopoly. Shortly after, Browning West disclosed an estimated 3.5% position along with a public letter criticizing Cooper’s lack of strategic focus, misaligned management incentives, and inadequate board oversight. The firm nominated four new board candidates and urged the Company to evaluate strategic alternatives for CooperSurgical.
Cooper’s response came in December 2025: the Company replaced its long-serving board chair and previous CEO (2007-2018) Robert Weiss. Mr. Weiss was succeeded by Colleen Jay, a nine-year director who was previously a senior executive at Procter & Gamble, where she led several major brands and, notably, successful divestitures. The Company also added a total-shareholder-return component to its executive compensation, and announced a formal strategic review.
The economic case for change is clear: a standalone CooperVision, with ~$2.7 billion in revenue, would be a pure-play leader in an attractive oligopoly and could plausibly command a premium multiple to the combined company. CooperSurgical, with disparate product lines and ~$1.4 billion in revenue (61% office/surgical, 39% fertility), is a less obvious strategic fit and management has reported receiving “robust interest” from third parties including “a sufficient number of parties that have given indications of interest, that are on the entire business. That’s how we’re moving forward.”
Balance Sheet and Capital Allocation
As well as the potential restructuring, Cooper is accelerating its capital returns. The Company does not currently pay a dividend (a small semi-annual payout was terminated in fiscal 2023), but it resumed share repurchases in fiscal 2025 for the first time since FY 2022. The authorization was increased to $2 billion, which is well-supported by Cooper’s three-year (FY 2026 – FY 2028) free cash flow guidance of up to $2.2 billion. This was raised from the $2 billion previous guidance (despite an extra >$200 million in litigation reserves), supported by a cost-reduction plan and a decline in capital expenditures following the necessary expansion of its MyDay contacts production facilities.
The balance sheet is also in strong shape, with leverage (net debt/ttm adjusted EBITDA) of ~2x (excluding the settlement for litigation regarding the LifeGlobal recall) within a comfortable range even prior to any proceeds from the CooperSurgical review. Management did note that a “significant portion” of the proceeds from a sale of CSI would “be used for share buybacks.”
We would also note that CEO Albert White also personally purchased 10,000 shares in September 2025 at approximately $68, slightly above the current share price.
Valuation
Over the past 15 years, the Cooper Companies’ stock has generally traded within a range of 13x-25x ttm EBITDA (along with a spike to ~33x during 2021). Today, it finds itself toward the bottom end of this range— at just 13.2x EV/EBITDA—despite solid FY 2025 results, a healthy balance sheet, accelerating free cash flow, increased share repurchases, and a clear catalyst with the pending simplification of CooperSurgical.
Additionally, the medium-term outlook for the Company’s core contact lens business has improved, with industry estimates suggesting an acceleration in growth from the historical 4%-6% to an estimated 6.5% CAGR through 2032. Combined with Coopers’ strength in pediatric myopia, we believe that the current discount to the Company’s historical valuation appears unwarranted.
We therefore value Cooper stock using its historical 5-year average of 18x EV/EBITDA, which produces an intrinsic value of $124 per share. This represents material upside of ~88% from the current share price, but we would note that our FY 2027 estimates for EBITDA are below consensus, and this FY 2027 intrinsic value estimate represents just an ~12% premium to the share price high of ~$111 in 2024.
Boyar’s Final Word
The Cooper Companies offers a high-quality, oligopolistic franchise in an industry with long-term structural growth, with a category-leading myopia-management position. We believe the strength of this business is currently being overshadowed by the CooperSurgical division, which is both less desirable and overly complex. However, with a resolution for this complexity on the horizon, an acceleration in free cash flow and share repurchases, a decade-plus low in valuation, we can clearly see a path to a brighter future for Cooper.
Important Disclosures. The information herein is provided by Boyar’s Intrinsic Value Research LLC (“Boyar Research”) and: (a) is for general, informational purposes only; (b) is not tailored to the specific investment needs of any specific person or entity; and (c) should not be construed as investment advice. Boyar Research does not offer investment advisory services and is not an investment adviser registered with the U.S. Securities and Exchange Commission (“SEC”) or any other regulatory body. Any opinions expressed herein represent current opinions of Boyar Research only, and no representation is made with respect to the accuracy, completeness or timeliness of the information herein. Boyar Research assumes no obligation to update or revise such information. In addition, certain information herein has been provided by and/or is based on third party sources, and, although Boyar Research believes this information to be reliable, Boyar Research has not independently verified such information and is not responsible for third-party errors. You should not assume that any investment discussed herein will be profitable or that any investment decisions in the future will be profitable. Investing in securities involves risk, including the possible loss of principal. Important Information: Past performance does not guarantee future results. The company mentioned in this sample are for informational purposes only and the performance of the stock selected is not indicative of the performance of the stocks profiled in Boyar Research, the performance of the stocks selected, and the performance of Boyar Research may in fact diverge materially. Additional information regarding the performance of other companies in Boyar Research is available upon request.
This information is not a recommendation, or an offer to sell, or a solicitation of any offer to buy, an interest in any security, including an interest in any investment vehicle managed or advised by affiliates of Boyar Research. Any information that may be considered advice concerning a federal tax issue is not intended to be used, and cannot be used, for the purposes of (i) avoiding penalties imposed under the United States Internal Revenue Code or (ii) promoting, marketing or recommending to another party any transaction or matter discussed herein. Clients of an affiliate of Boyar Research and employees of Boyar Research own shares in COO.